Medicare, and paying for care on your own

What Medicare pays for at home, what it doesn’t, and how families pay for the rest.

At a glance2026
Reviewed Oct 2026
  • Original MedicareShort-term skilled care only
  • Everyday help aloneNot covered
  • Medicare AdvantageSome plans include help at home
  • Dementia respiteUp to $2,625 a year
  • Open enrollmentOct 15 to Dec 7

What Original Medicare covers at home

Medicare pays for short-term skilled care at home. It doesn’t pay for everyday help on its own.

  • Part-time nursing or therapy that a doctor orders.
  • For someone who is mostly homebound.
  • A home health aide, but only alongside that skilled care.
  • From a Medicare-certified home health agency.

Medicare doesn’t pay for bathing, dressing, meals or housekeeping when that’s the only help you need. That’s where the options below come in.

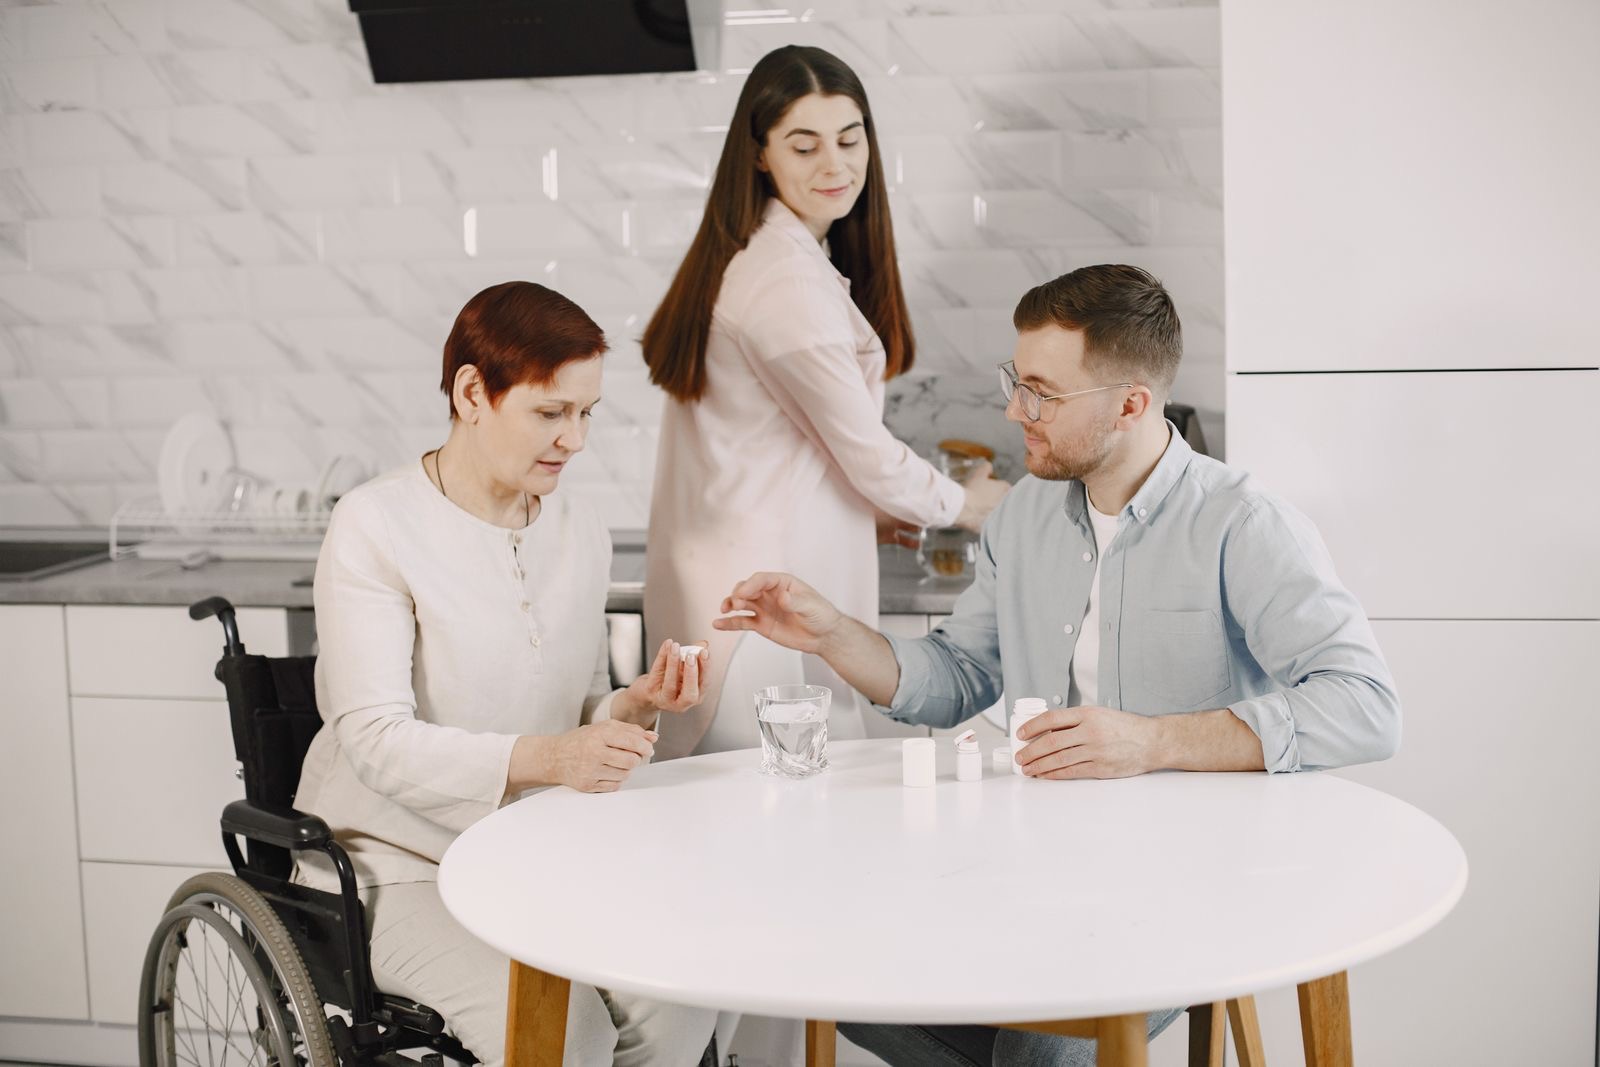
A caregiver helping an older woman with her medication at the kitchen table

How to start

How most families cover everyday help.

  1. Check your Medicare Advantage plan

    Some plans include in-home help hours. Look in your Evidence of Coverage or call the number on your card.

    Plan papers
  2. Look for other coverage

    Long-term care insurance, a life insurance care rider, or VA benefits may pay. See the guides below.

    Other coverage
  3. Use the tax breaks

    Home care can count as a medical expense, and work-related care costs may qualify for a credit.

    Tax time
  4. Start with the hours you need

    With us, paying on your own is month to month. Add hours as needs grow.

    Month to month

Good to know

The questions families ask most.

Medicare Advantage help at homeSome plans include it.

In 2026, about 7% of Medicare Advantage plans, and 25% of special needs plans, list in-home support. Hours are limited and some plans use their own vendor.

Open enrollment runs October 15 to December 7, 2026. Free Medicare counseling (SHIP): (800) 548-9034.

Dementia respite (GUIDE)For Original Medicare.

GUIDE programs pay for respite, up to $2,625 a year in 2026, for people living with dementia who have an unpaid family caregiver. The money goes to the program, not the family.

Chicago-area programs include UChicago Medicine, Rush and the Advocate Memory Center. Ask the doctor or memory clinic.

Tax breaksCare can count as a medical expense.

If a doctor, nurse or licensed social worker certifies that someone needs help with 2 daily tasks or has serious memory loss, and care follows a plan, home care can count as a medical expense. Medical costs above 7.5% of income are deductible.

Pay to a relative usually doesn’t count unless they’re licensed. If you work, a dependent care account or credit may help. Ask a tax professional.

Health savings accountsHSA money can pay for qualified care.

Money in a health savings account can pay for qualified long-term care services, as well as long-term care insurance premiums up to a limit.

Home equityA reverse mortgage, at 62 or older.

Some homeowners 62 and older use a reverse mortgage. You must meet with a HUD-approved counselor first. Talk with someone you trust before you sign anything.

Where VitalTouch fits

Paying on your own is simple with us. No long contracts.

  • Month to monthNo minimums. Change hours any time.
  • Itemized invoicesUseful at tax time and for any insurance claim.
  • Switch laterIf a benefit comes through, we switch your billing over.
What we can do todayVitalTouch, Oct 2026
Honest answer
  • Care paid on your own, month to month
  • Itemized invoices
  • Help reading your Medicare Advantage benefit
  • Bill Original Medicare (it doesn’t cover this care)
(708) 726-4536Free coverage check

Other ways to pay

Sources

General information, not legal or benefits advice. Rules change, and each program decides for itself. Last reviewed October 12, 2026.

Ready to start small?

Tell us what you need. We’ll suggest the hours.